Storm damage claim specialists for homeowners
RSL Claims manages storm damage insurance claims across the North West of England and North Wales, assessing the loss and dealing with insurers on your behalf through settlement.
Regulation
Experience
20+ years · Founded 2003
Response
24/7 support · On site within 24h
Full claim scope
Damage and costs covered by a storm damage claim
The process
How we manage your storm damage insurance claim
We assess the damage, gather evidence and negotiate with insurers, giving you independent claim advice and keeping your storm damage claim focused on fair settlement.
1
Free consultation
We inspect your home, review property-related insurance cover and explain the insurance claims process, setting expectations for each stage of the claim process.
2
Immediate protection
We advise on temporary protection and preserving evidence when making a claim, with help with your insurance claim that protects your position.
3
Damage evidence
Our experience with storm losses helps us gather photographs, weather records, maintenance evidence and estimates to document the insurance loss.
4
Claim negotiation
We prepare the claim on your behalf and deal with the insurance company, drawing on our experience across the insurance industry.
5
Settlement and repairs
We monitor work, payments and outstanding claim solutions until repairs are complete and your home is restored.
Has storm damage left your home exposed?
Need insurance claim help or help with storm damage claims? Tell us what happened and we’ll respond within 1 working hour.
Recent settlements
+30–50% above insurer’s first offer
Range achieved across recent claim settlements. We treat each claim on its own merits – and never settle for the first number on the table.
Founder · Chartered Loss Adjuster
Talk to the founder
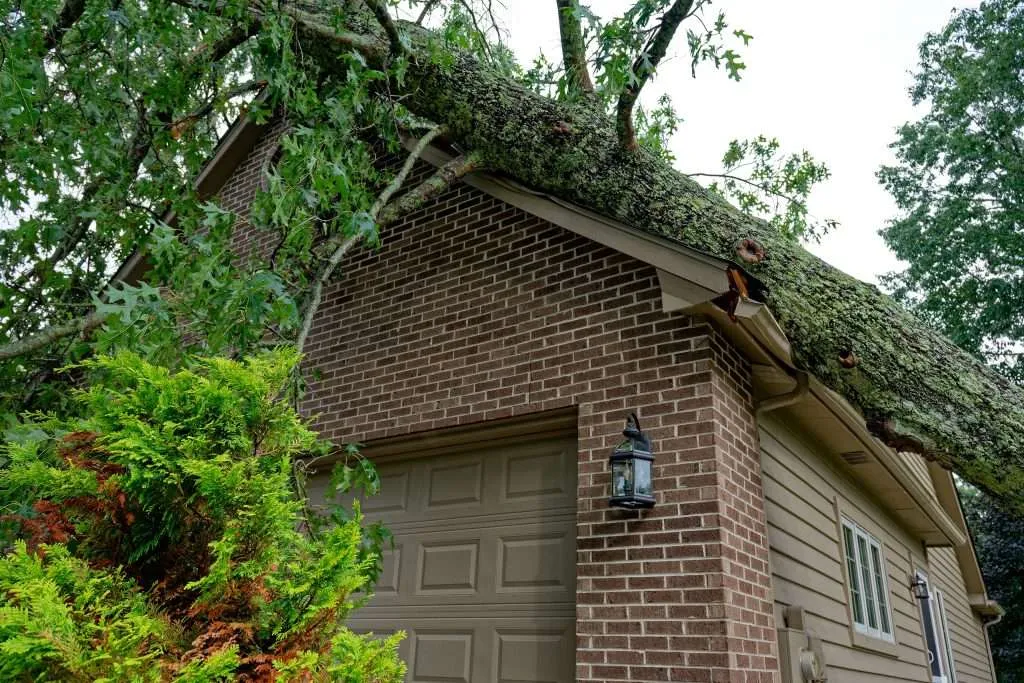
Storm damage can be more extensive than it first appears
From ground level, roof damage may look limited to a few missing tiles. Once water enters the roof space, the claim can also involve insulation, ceilings, electrics and structural repairs. An early inspection helps make sure the full repair scope is identified before settlement.
Rob Spence – Managing Director, Chartered Loss Adjuster.
Frequently asked questions
Common questions about storm damage insurance claims
What should I do immediately after a storm damages my home?
Keep away from damaged roofs, loose masonry and ceilings that may be unsafe. Take photographs safely, move belongings away from incoming water and arrange temporary protection where needed. Notify your insurer and keep receipts for emergency work.
Does home insurance cover storm damage?
Many policies cover sudden damage to homes following severe weather. Contents insurance may cover belongings damaged by water or debris. Exact cover depends on the wording, limits and exclusions in your policy.
How will my insurer decide whether the weather counted as a storm?
The insurer may consider local records, the timing and location of the event, the damage pattern and your property’s earlier condition. Weather data alone does not always prove the damage was caused by a storm.
What if my insurer says the damage was caused by wear and tear?
Ask for the decision and supporting evidence. Our insurance claims consultants can review photographs, surveys, maintenance records and repair history, then respond where the insurer’s view does not reflect the circumstances or available evidence.
Can I make a storm damage roof insurance claim for water damage inside?
Where insured roof damage allows rainwater into your home, the claim may also cover damage to ceilings, walls, insulation, flooring, electrics, decoration and contents.
What evidence helps with roofing insurance claims for storm damage?
Useful evidence includes dated photographs, weather records, roof inspections, contractor reports, maintenance documents, repair estimates and receipts. This can show the timing, cause and full scale of the insured loss.
Can I arrange emergency roof repairs before the insurer visits?
You can take reasonable steps to prevent further damage, but temporary work is usually safer than permanent repairs straight away. Photograph the damage beforehand, retain damaged materials where practical and keep all invoices and written records for repairs to your property.
Can I claim for alternative accommodation?
Your policy may fund suitable temporary accommodation if storm damage leaves your home unsafe or without necessary facilities. We help explain the need, likely duration and reasonable costs to the insurer.
Do you handle storm damage insurance claims in my area?
RSL Claims supports homeowners across the North West of England and North Wales, including Liverpool, Wirral, Manchester, Warrington, Chester, Wrexham and surrounding areas.
Get in touch
Free, no-obligation consultation on your storm damage claim.
Tell us briefly what happened and we’ll come back to you as soon as possible. If we can help, our FCA-regulated loss assessor will tell you honestly. If we can’t, we’ll point you in the right direction. We cover the North West of England and North Wales.
Water
Burst pipes & water damage
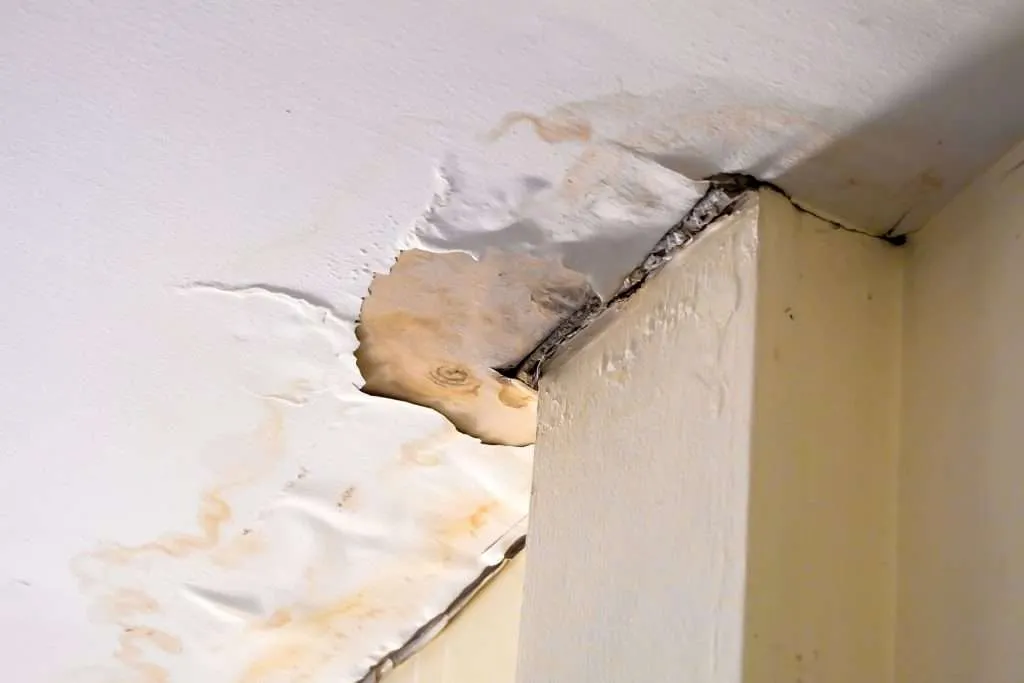
We help identify the source of damage, coordinate drying and repairs and present the full claim to your insurer.
Subsidence
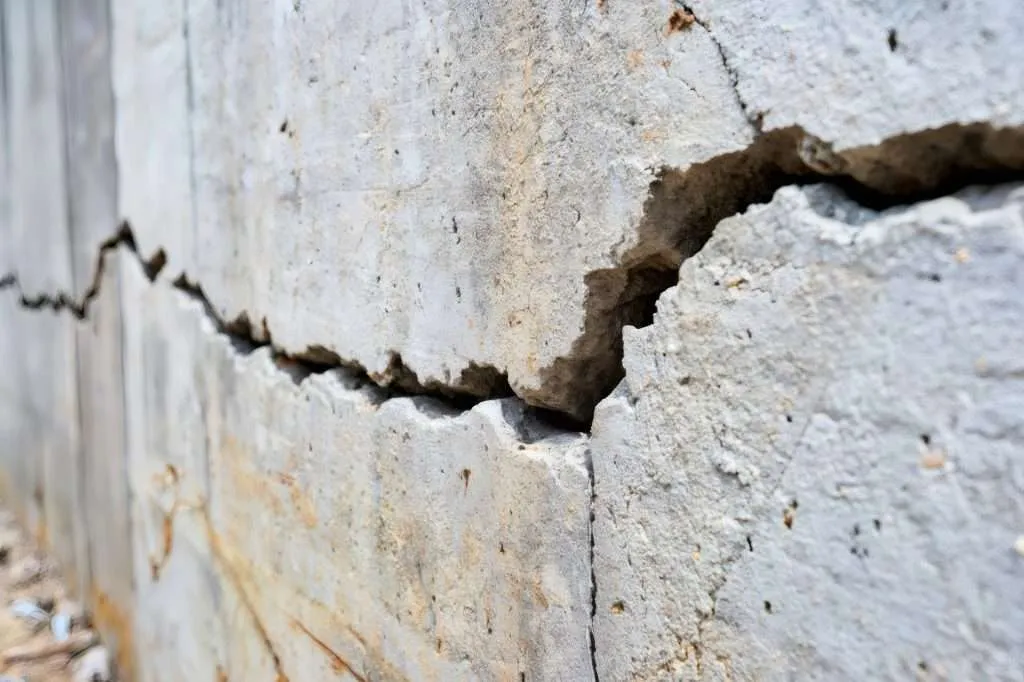
Subsidence
Long-term and complex claims requiring specialist oversight, including monitoring, surveys and structural repairs.
Impact
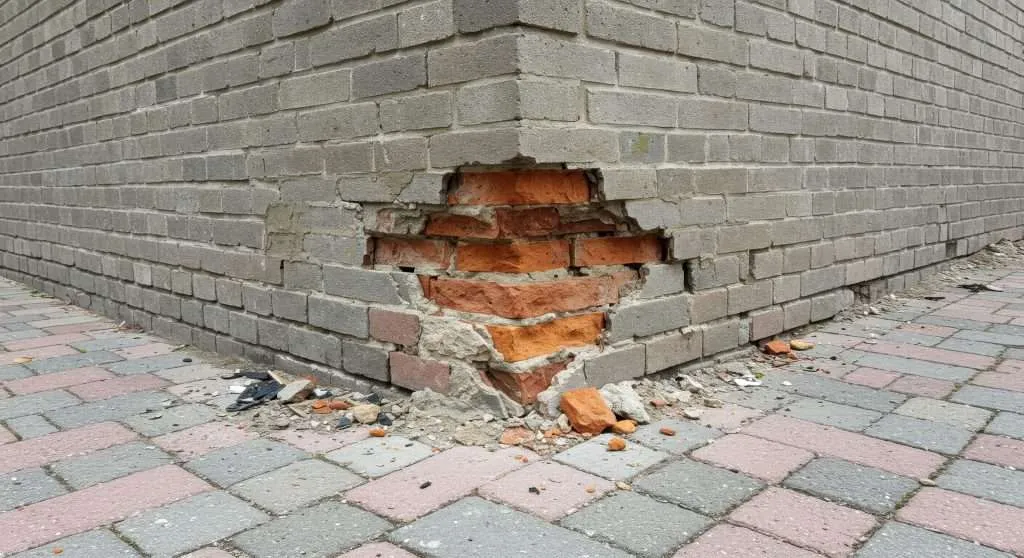
Impact damage
Damage caused by vehicles, falling objects or structural impact is assessed and managed from start to finish.