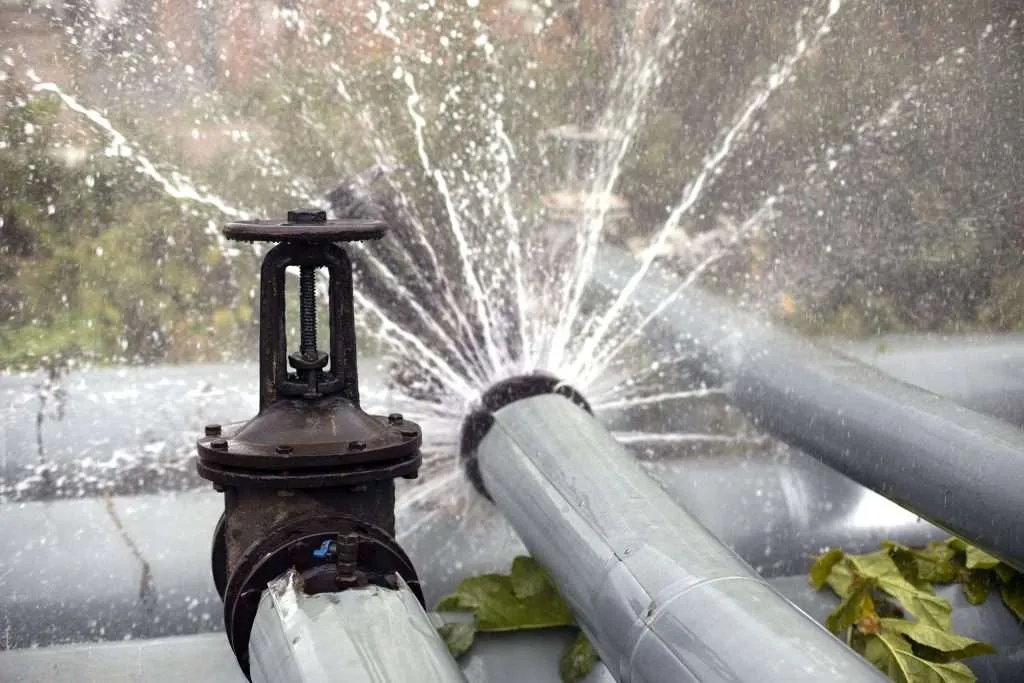
Burst pipe damage insurance claims managed with clarity and care
We manage your burst pipe damage insurance claim from start to finish. We assess the damage, manage the entire process, and negotiate with the insurance company to make sure your claim is successful.
Regulation
Experience
20+ years · Founded 2003
Response
24/7 support · On site within 24h
Full claim scope
Making sure your claim covers the total impact of water damage
The process
How we handle your burst pipe damage insurance claim
From your initial call through to settlement, we manage the assessment, evidence, insurer liaison and repair timeline, allowing you to focus on getting your home back to normal.
1
Free home visit and policy review
We visit your home promptly for a free site survey, mapping the path of the water, taking damp readings and reviewing your policy for ‘Trace and Access’ or ‘Alternative Accommodation’ coverages.
2
We take over the claim
Once appointed, we deal with your insurer and their loss adjuster on your behalf. We help arrange urgent works, leak detection, drying specialists, temporary accommodation and interim payments where your policy allows.
3
We evidence the full loss
We prepare your claim with photographs, damp readings, surveyor input, drying records, repair schedules, contents lists and contractor costings. The aim is to capture the full cost of reinstating your home, not just the surface damage.
4
Negotiation and settlement
We deal directly with the insurer’s loss adjuster, challenge any attempt to limit the claim unfairly and negotiate a settlement that reflects the full damage and your policy cover.
5
Repairs and sign-off
Our vetted contractors can carry out the reinstatement works, with your approval throughout. We help recover any outstanding payments and only sign off once the repairs are complete and you are happy with the outcome.
Recently had a burst pipe or water leak at home?
Tell us what happened – we’ll come back within 1 working hour. Free consultation, no obligation.
Recent settlements
+30–50% above insurer’s first offer
Range achieved across recent claim settlements. We treat each claim on its own merits – and never settle for the first number on the table.
Founder · Chartered Loss Adjuster
Talk to the founder
Water damage is one of the most deceptively complex claims a homeowner can face.
Escape of water claims are one of the most common types of property loss, yet saturated subfloors and trapped moisture are often invisible to an insurance company’s loss adjuster. If a pipe has burst due to either a frozen pipe or high water pressure, I’ve seen these ‘hidden’ costs ignored on almost every water damage insurance claim I’ve handled in 20 years.
Rob Spence – Managing Director, Chartered Loss Adjuster.
Frequently asked questions
Common questions about burst pipe and water leak claims
What should I do first after a burst pipe or water leak?
Immediately turn off the water at the stopcock (usually under the kitchen sink) to stop the water flow. You should drain the system and turn off the electricity at the mains if water is near electrical outlets. Contact your insurer only after documenting the leak and any damage.
Does home insurance cover burst pipe damage?
Home insurance policies cover what is often referred to as ‘escape of water’, which is typically covered under buildings insurance and contents insurance. As a result of a water escape, the policy will cover any costs incurred to repair your property or replace your contents. Generally speaking, it is the property owner’s responsibility to repair the cause of the damage, unless they have specific home emergency cover.
Is a burst pipe claim different from a flood damage claim?
A pipe insurance claim for escape of water is different from house insurance for water entering from outside. We manage all claims related to your property and navigate the related insurance terms to make sure the correct policy wording is applied to your loss.
Can I claim for trace and access?
Many homeowners don’t realise that ‘Trace and Access’ is often a separate limit on their policy. We make sure that the costs of tearing out and reinstating tiled walls or floors to find the leak are itemised correctly so you don’t end up paying for the ‘access’ out of your own pocket.
Why does the drying programme matter?
Insurers can push for a quick ‘surface dry’ to save costs. However, if deep-seated moisture isn’t extracted from structural timbers or subfloors, you risk secondary damage like dry rot or toxic mould months after the claim is closed. We insist on professional moisture mapping and certified drying certificates before any repairs begin.
What if my insurer says the damage is minor?
This can happen with water leak damage insurance claims, especially when hidden areas have not been inspected. We assess the full damage, gather supporting evidence and challenge the insurer’s position where it does not reflect the true cost of repair.
What if my insurer says the leak was caused by wear and tear?
Insurers may dispute the cause of the leak or try to exclude part of the claim. We review the policy, assess the evidence and separate the cause of the leak from the damage caused by the escaping water.
Can I claim for alternative accommodation?
If your home is unsafe, lacks working facilities or cannot be lived in during drying and repairs, your policy may cover alternative accommodation. We help present the need clearly and include reasonable costs within the claim.
How long does a home insurance claim for water damage take?
It depends on the scale of the damage, drying time, access issues and how quickly the insurer responds. Smaller claims may settle in weeks. Larger claims involving floors, ceilings, electrics, kitchens, bathrooms or alternative accommodation can take longer. Early support helps keep the process moving.
The loss adjuster is saying I don’t have matching sets cover.
Matching sets coverage is generally found in the more premium-level policies. Matching sets cover allows the replacement of undamaged items, such as kitchen units or tiling, if only a small amount has been damaged.
What can I do if I don’t have matching sets cover.
We have extensive experience dealing with these issues and aim to present your claim in the best possible terms. We thoroughly examine all items, damaged or otherwise and then look at the practical arguments / costs in keeping the undamaged items. More often than not we can put together a compelling argument for significant contributions.
Get in touch
Free, no-obligation consultation on your home insurance claim for water damage
Tell us briefly what happened and we’ll come back to you as soon as possible. If we can help, our FCA-regulated loss assessor will tell you honestly. If we can’t, we’ll point you in the right direction. We cover the North West of England and North Wales – and travel further than 100 miles when a claim warrants it.
Flood
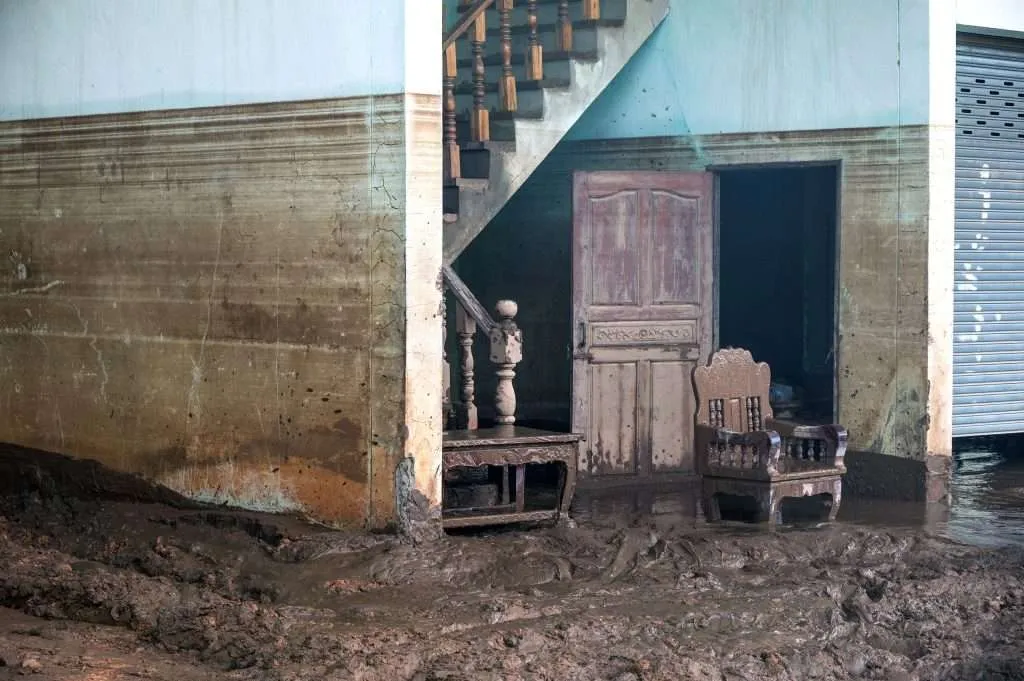
Flood damage
From drainage failures to severe flooding, we oversee surveys, strip-out works and reinstatement.
Storm
Storm damage
Roof damage, fallen trees and water ingress claims are professionally documented and negotiated.
Fire
Fire damage
From kitchen fires to major property losses, we manage the assessment, repairs and negotiations on your behalf, working to help you receive a fair settlement.