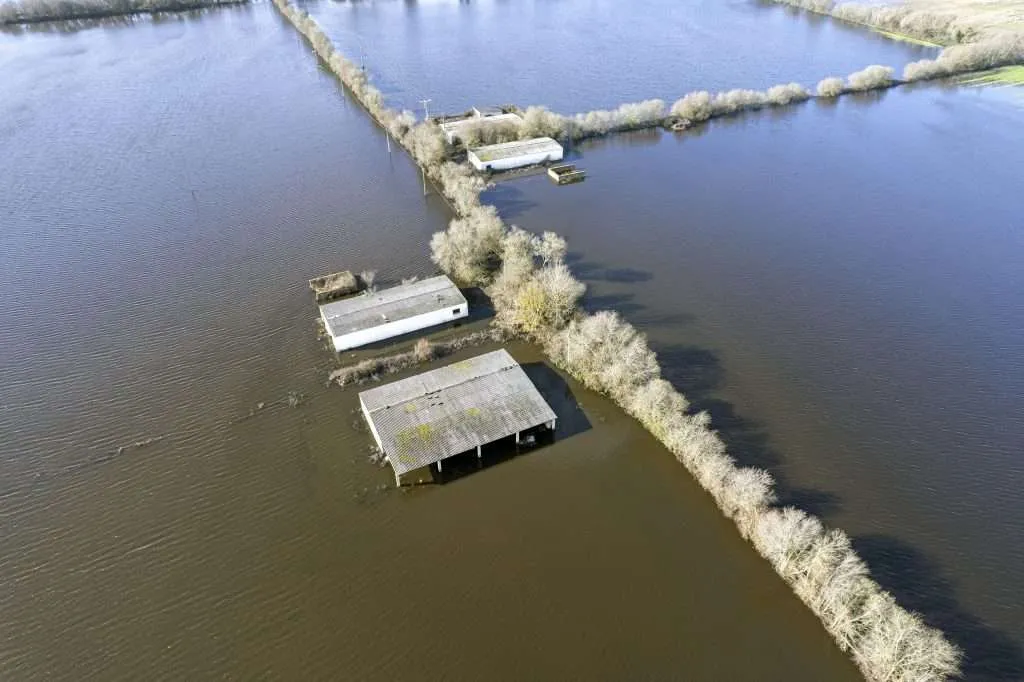
Commercial flood damage claims assessed, managed and negotiated
Independent commercial flood damage insurance loss assessors helping businesses evidence water damage, deal with insurers and move their claim towards a fair settlement.
Regulation
Experience
20+ years · Founded 2003
Response
24/7 support · On site within 24h
Full claim scope
Costs your commercial water damage claim may need to cover
The process
How we manage your commercial water damage claim
We step in early to assess the damage, secure the right evidence and keep the claim moving. You get clear advice from a loss assessor authorised by the Financial Conduct Authority, direct support with your insurer and a stronger basis for settlement.
1
Free site visit & policy review
We visit your premises, review the cause of the damage and check your commercial insurance policy for flood, escape of water, contents, stock, business interruption and additional cost cover.
2
Damage assessment and evidence
We record visible damage, check for areas where water may have spread and support the investigation with specialist reports, drying records, contamination advice or contractor input where needed.
3
Claim preparation
We prepare a clear commercial flood insurance claim covering building repairs, drying, reinstatement, stock, equipment, contents, temporary premises and business interruption where applicable.
4
Negotiation with the insurer’s loss adjuster
We deal with your insurer and their loss adjuster, respond to queries, challenge low or narrow assessments and negotiate using evidence from the site, contractors and supporting specialists.
5
Repairs, payments and sign-off
Our team helps coordinate reinstatement with trusted commercial contractors, monitor progress, and work to recover agreed payments so your premises can return to proper use.
Has water damage disrupted your business?
Speak to an expert, independent commercial flood damage insurance claim consultant before decisions are made on drying, strip-out, repairs or settlement. Free consultation, no obligation.
Recent settlements
+30–50% above insurer’s first offer
Range achieved across recent claim settlements. We treat each claim on its own merits – and never settle for the first number on the table.
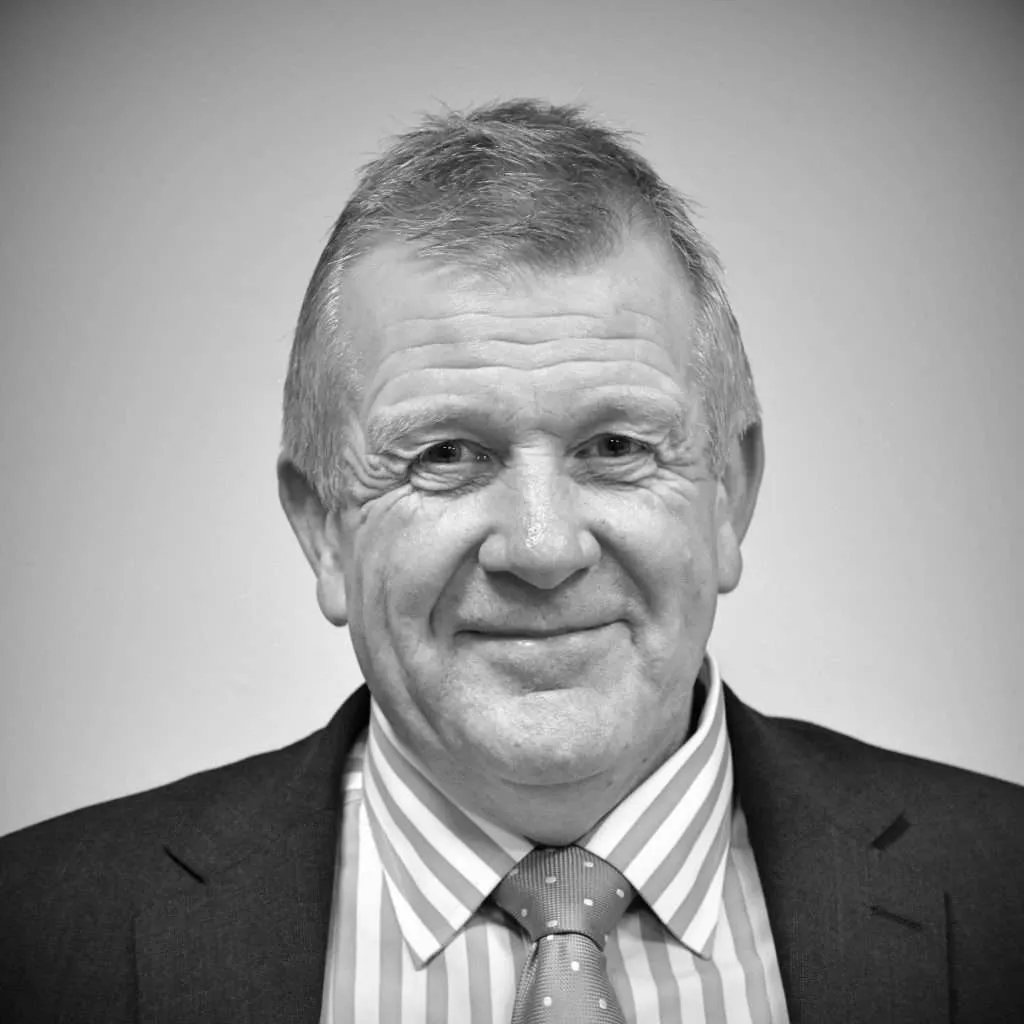
Founder · Chartered Loss Adjuster
Talk to the founder
Commercial water damage can affect more than the building.
When water gets into a commercial property, the damage is rarely limited to what you can see on day one. Drying, contamination, stock, equipment and business interruption all need to be looked at properly. Getting us involved early helps protect the evidence, avoid rushed decisions and give the claim the best chance of reaching a fair settlement.
Rob Spence – Managing Director, Chartered Loss Adjuster.
Frequently asked questions
Common questions about commercial flood and water damage claims
How soon should I contact a loss assessor after flood or water damage?
As soon as possible, especially if you need to make a claim for flooding, escape of water or wider business disruption. Early advice can help protect evidence, prevent unnecessary delays and make sure your flood insurance claim covers drying, strip-out, stock losses and business interruption properly from the start.
Can I start cleaning up before the insurer visits?
You can take reasonable steps to prevent further damage, but avoid disposing of damaged stock, equipment or materials without keeping evidence. Take photos, keep records and speak to us before major strip-out or removal where possible.
Will my insurer pay for drying works?
Drying works are often part of a valid commercial water damage claim, depending on the cause of the damage and your policy terms. We help check what is covered and make sure drying records are properly used as evidence.
What if the damage is hidden behind walls, floors or ceilings?
Hidden moisture is common in flood and escape-of-water claims. We can arrange inspections, moisture readings and specialist input to show the full extent of damage before repairs are agreed.
Can I claim for lost trading?
If you have business interruption cover, you can claim for lost income, ongoing overheads and extra costs caused by the disruption. We help prepare this part of the claim, so it isn’t treated as an afterthought.
Do I have to accept the insurer’s first offer?
No, if the offer does not reflect the full damage, repair cost or business impact, we can assist in challenging it. We review the insurer’s position, prepare evidence and negotiate any compensation with insurance companies on your behalf.
Get in touch
Free, no-obligation consultation on your flood claim.
Tell us briefly what happened and we’ll come back to you as soon as possible. If we can help, our FCA-regulated loss assessor will tell you honestly. If we can’t, we’ll point you in the right direction. We cover the North West and North Wales – and travel further than 100 miles when a commercial claim warrants it.
Interruption
Business interruption
We work alongside accountants and specialists to present lost income and increased cost claims properly.
Storm
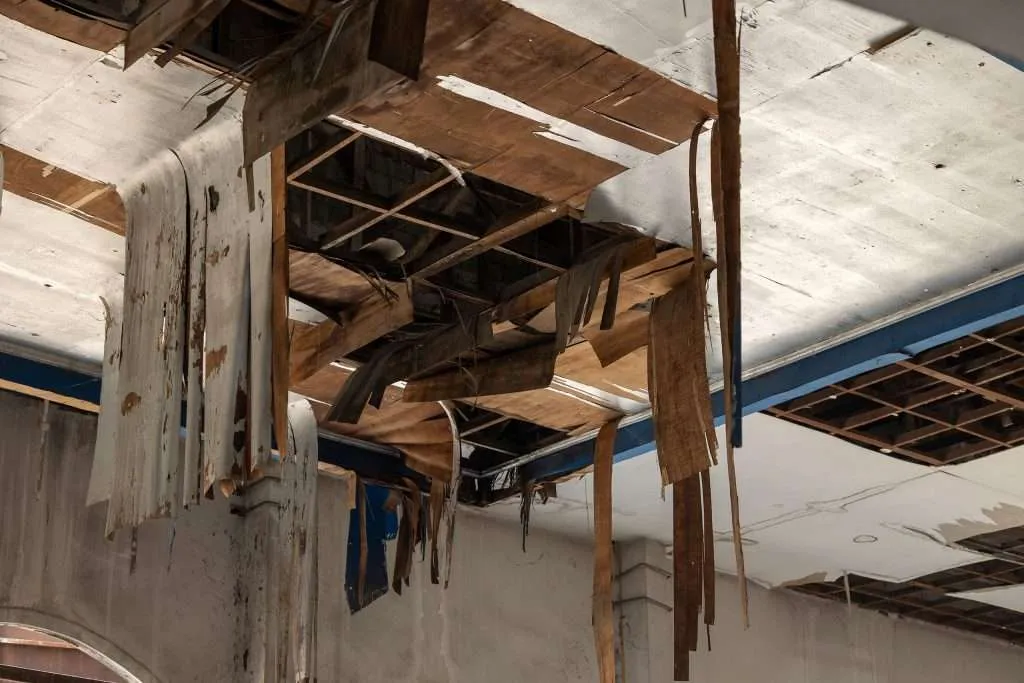
Storm damage
Claims relating to roofing, signage, structural damage and external property damage are handled professionally.
Impact
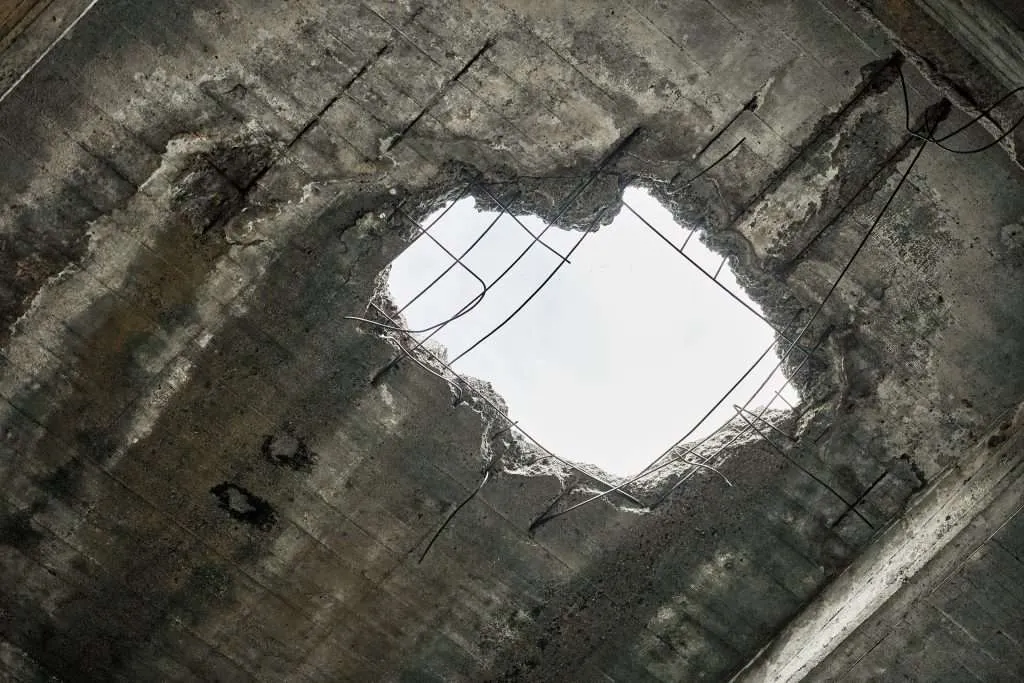
Impact damage
Vehicle impact and structural damage claims managed from assessment through to reinstatement.