Commercial storm damage insurance claims managed for you
Independent loss assessors managing business storm damage insurance claims across the North West of England and North Wales, from damage assessment through to settlement.
Regulation
Experience
20+ years · Founded 2003
Response
24/7 support · On site within 24h
Full claim scope
Losses your storm damage claim may need to include
The process
How we handle your commercial storm damage claim
We assess the damage, review your policy, gather evidence and deal with your insurer, keeping repairs, payments and reinstatement moving from the outset.
1
Free consultation
We discuss the event, review your policy and explain what may be covered, including buildings, contents, stock, emergency work and business interruption losses.
2
Inspect and advise
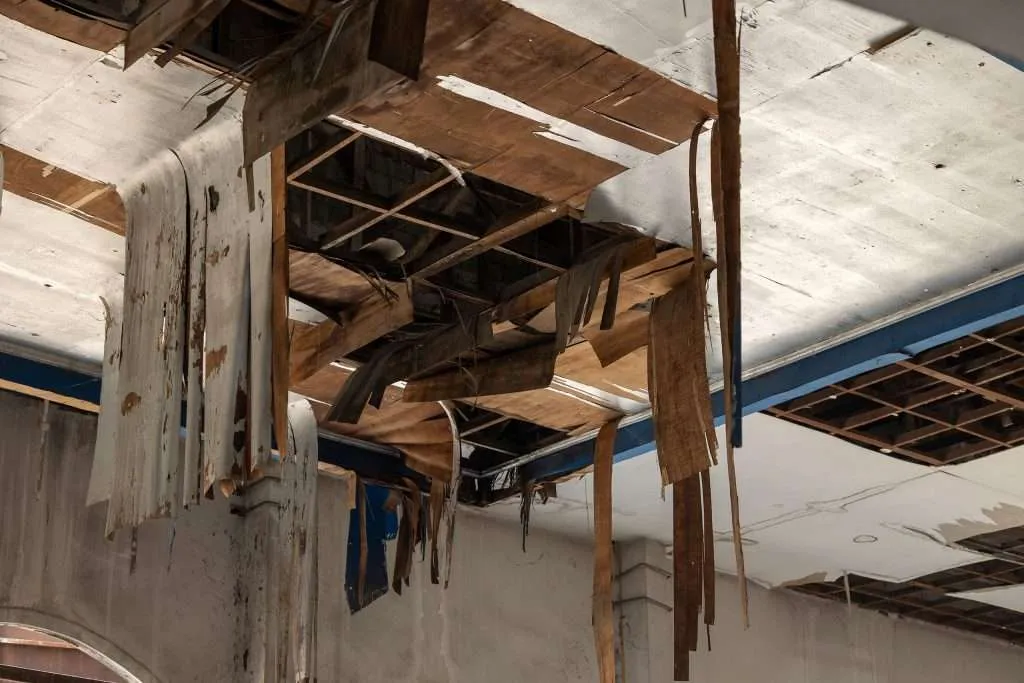
We inspect the premises when safe, record visible and hidden damage, identify urgent risks and advise on temporary measures needed to prevent further loss.
3
Evidence and preparation
We use Met Office records, data from the nearest weather station, photographs and maintenance documents to time the storm damage and provide photographic evidence of the loss.
4
Manage and negotiate
We prepare insurance claims for damage caused by wind, water and debris, challenging unsupported decisions that could lead the insurer to decline a claim.
5
Settlement and repairs
After the claim has been accepted, we monitor agreed repairs, payments and outstanding items until the work is complete and the claim is settled.
Has a storm damaged your business premises?
Before you make a claim or accept repairs, let RSL Claims independently review your claim for storm damage, policy wording and the insurer’s current position.
Recent settlements
+30–50% above insurer’s first offer
Range achieved across recent claim settlements. We treat each claim on its own merits – and never settle for the first number on the table.
Founder · Chartered Loss Adjuster
Talk to the founder
Storm damage claims often turn on the cause, not just the repair cost.
Insurers may point to wear and tear or an existing defect. Early evidence of the weather, the building’s condition and the full damage helps us present the claim clearly and keep repairs moving.
Rob Spence – Managing Director, Chartered Loss Adjuster.
Frequently asked questions
Common questions about commercial storm damage insurance claims
What should I do if my premises are damaged by a storm?
Keep people away from unsafe areas, take photographs from a safe position and prevent further loss where possible. Contact your insurer or insurance broker promptly, but avoid agreeing to permanent repairs before the full damage is assessed.
How will the insurer decide if the weather was a storm?
The insurer should carefully consider all the evidence to decide whether the reported event meets the policy wording. Weather records, the damage pattern and the building’s prior condition may all affect whether they consider a storm to be the cause.
What if the insurer says the damage was wear and tear?
Ask for the decision and supporting evidence in writing. We can review maintenance records, photographs, surveys and repair history, then respond where the insurer’s conclusions do not reflect the circumstances.
Can I claim for internal water damage and lost trading?
Where insured storm damage allows water inside, the resulting repairs may form part of the claim. Business interruption cover may also include lost income, continuing costs and reasonable extra operating expenses.
Can RSL Claims help after my insurer has inspected?
Yes, we can review the existing assessment, identify missing or undervalued items and take over communication where the claim is delayed, restricted or disputed.
Can you help with a complaint about the claim?
We review complaints about storm damage claims and wider complaints about insurance claims, checking the policy, evidence, repair scope and insurer’s reasons before explaining your options.
Is storm damage considered accidental damage by insurers?
Storm damage is usually considered under the storm section of a policy rather than accidental damage cover. Where a storm claim is declined, accidental damage cover may still apply, depending on the policy wording and exclusions.
Do you handle commercial storm damage insurance claims in my area?
RSL Claims supports businesses across Liverpool, the Wirral, Manchester, Warrington, Chester, Wrexham, the wider North West of England and North Wales.
Get in touch
Free, no-obligation consultation on your commercial storm damage claim.
Tell us briefly what happened and we’ll come back to you as soon as possible. If we can help, our FCA-regulated loss assessor will tell you honestly. If we can’t, we’ll point you in the right direction. We cover the North West of England and North Wales.
Fire
Fire damage
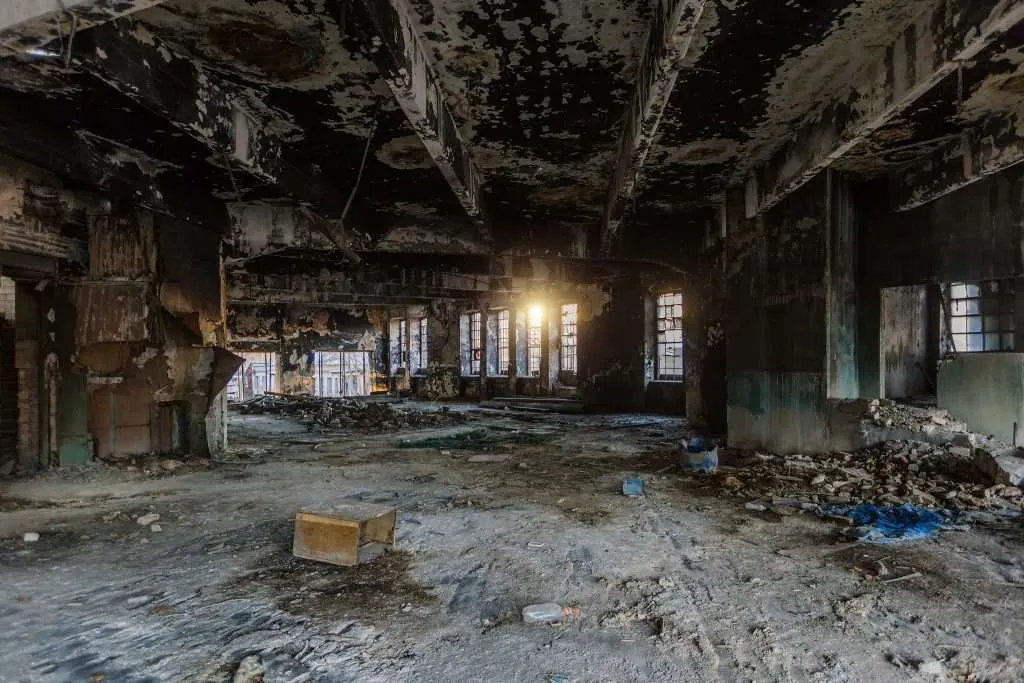
Helping businesses recover from property damage, stock loss and operational disruption.
Flood
Flood damage
Managing surveys, repairs and reinstatement while helping keep your business operational where possible.
Interruption
Business interruption
We work alongside accountants and specialists to present lost income and increased cost claims properly.