Business interruption claims handled on your behalf
When an unexpected event affects trading, RSL Claims helps establish the financial loss, prepare business interruption insurance claims and deal with the insurer on your behalf.
Regulation
Experience
20+ years · Founded 2003
Response
24/7 support · On site within 24h
Full claim scope
What a business interruption claim can include

The process
How we handle your business interruption insurance claim
We establish how trading has been affected, review the relevant documents and organise the evidence needed to support the financial loss throughout the claims process.
1
Free consultation and policy review
We discuss what happened and review your business interruption insurance policy to identify the applicable terms, limits and period of cover.
2
Assess the impact
We look at closure, reduced capacity, restricted access, cancelled work and other factors that may have left the organisation unable to operate as normal.
3
Establish the financial loss
We review accounts, management information and trading records to understand the loss of income and build a realistic picture of expected performance.
4
Prepare and present the claim
We organise the calculations and supporting evidence before presenting the claim to the insurance company and responding to questions about the figures.
5
Negotiate through
to settlement
We deal with the insurance provider, update the figures where needed and negotiate towards an agreed settlement.
Has an insured event affected your ability to trade?
If you’re dealing with a business interruption claim, RSL Claims can review the financial loss, assess the policy position and provide claim advice before settlement, including where the interruption sits alongside property damage or repairs.
Recent settlements
+30–50% above insurer’s first offer
Range achieved across recent claim settlements. We treat each claim on its own merits – and never settle for the first number on the table.
Founder · Chartered Loss Adjuster
Talk to the founder
Your claim should reflect how your business actually trades.
A business can be back open and still be feeling the financial impact of an insured loss. We look beyond the immediate disruption, using the policy and trading records to understand the full loss and make sure the claim reflects how the business would otherwise have performed.
Rob Spence – Managing Director, Chartered Loss Adjuster.
Frequently asked questions
Common questions about business interruption claims
Is business interruption insurance a legal requirement?
Business interruption insurance is not generally a legal requirement in the UK. It is usually optional cover that businesses choose to protect against the financial impact of certain insured events.
Is business interruption insurance included with buildings and contents cover?
Business interruption insurance may be included within a wider business insurance package or sold as an add-on to buildings insurance or contents insurance. The exact cover depends on the policy.
Does business interruption insurance always require physical damage?
Business interruption insurance can provide cover following insured property damage such as fire, flood, storm or escape of water. The policy wording will state if cover applies or not.
What happens if my business suffers a fire?
If your business suffers a fire, the property damage claim and business interruption claim may run alongside each other. The interruption element can account for the financial impact on trading while the business recovers.
What if my business holds a lot of stock or equipment?
If your business relies on a lot of stock or equipment, damage to those assets may have a direct effect on trading. The business interruption claim may need to show how that damage reduced sales, production or normal business operations.
What if only one business premise is affected?
If only one business premise is affected, the impact will depend on how that site contributes to the wider business. For multi-site companies, the effect on other locations may also need to be considered.
What if the policyholder has different types of commercial insurance?
Where a policyholder has several types of insurance, each section should be checked separately. Property, liability and business interruption cover can respond differently to the same incident.
Can RSL Claims help if my business interruption claim has already started?
Yes, RSL Claims can review an existing claim, assess how the loss has been presented and take over discussions with the insurer where appropriate.
Get in touch
Free, no-obligation consultation on your business interruption claim.
Tell us briefly what happened and we’ll come back to you as soon as possible. If we can help, our FCA-regulated loss assessor will tell you honestly. If we can’t, we’ll point you in the right direction. We cover the North West and North Wales – and travel further than 100 miles when a commercial claim warrants it.
Water
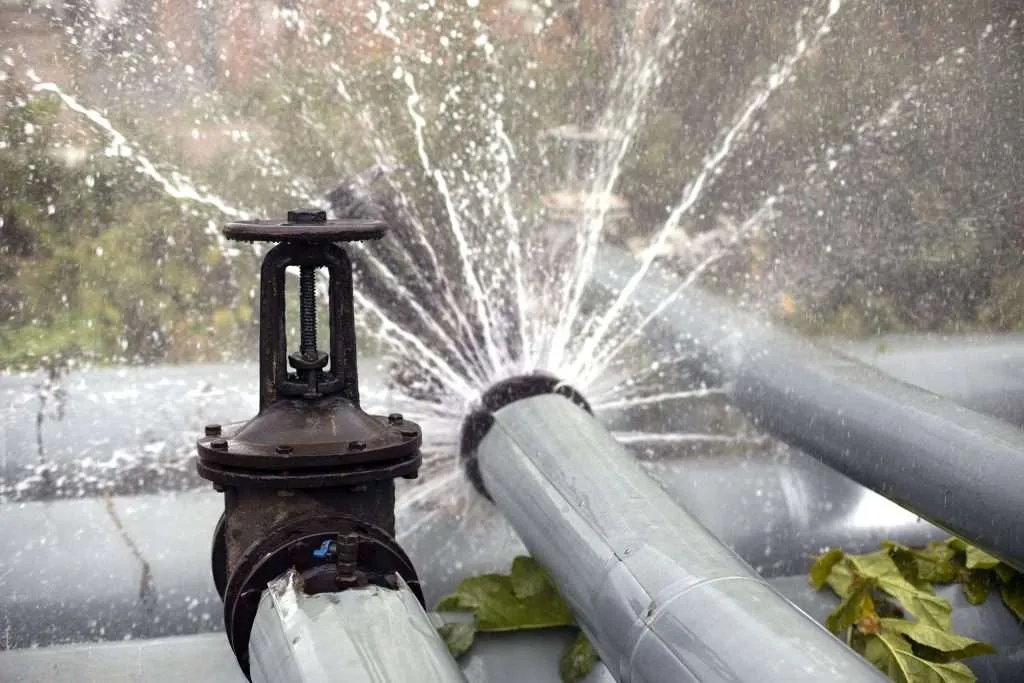
Burst pipes & water damage
We coordinate drying, repairs and claim management while helping minimise disruption to your business.
Impact
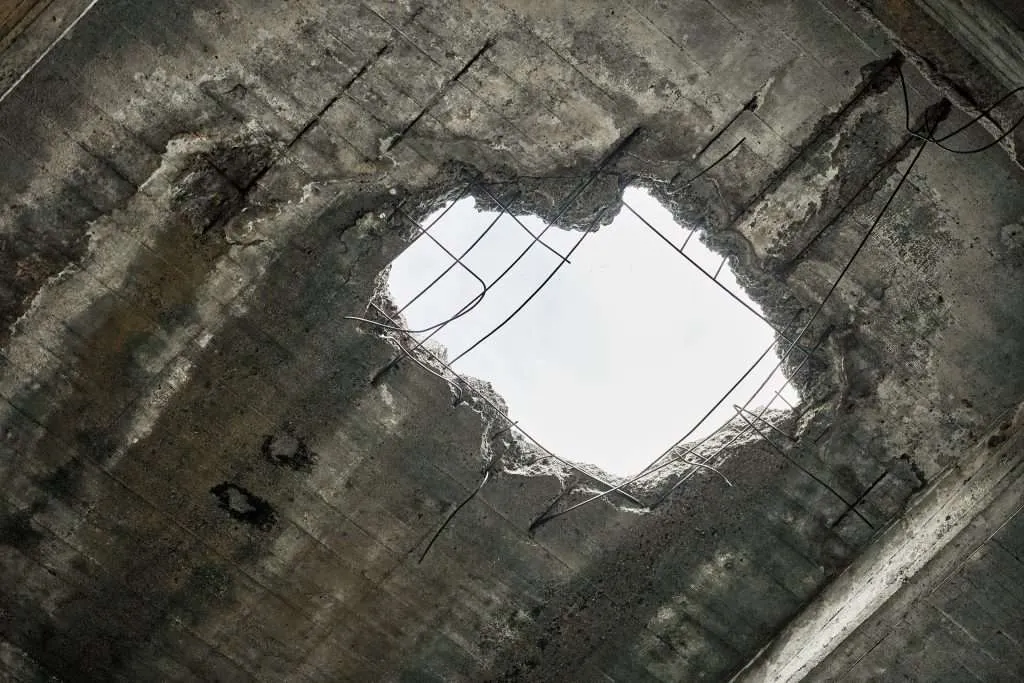
Impact damage
Vehicle impact and structural damage claims managed from assessment through to reinstatement.
Contents
Damaged contents
From office equipment to specialist machinery, we document and manage business contents claims clearly and professionally.