Flood damage insurance claim consultants you can rely on
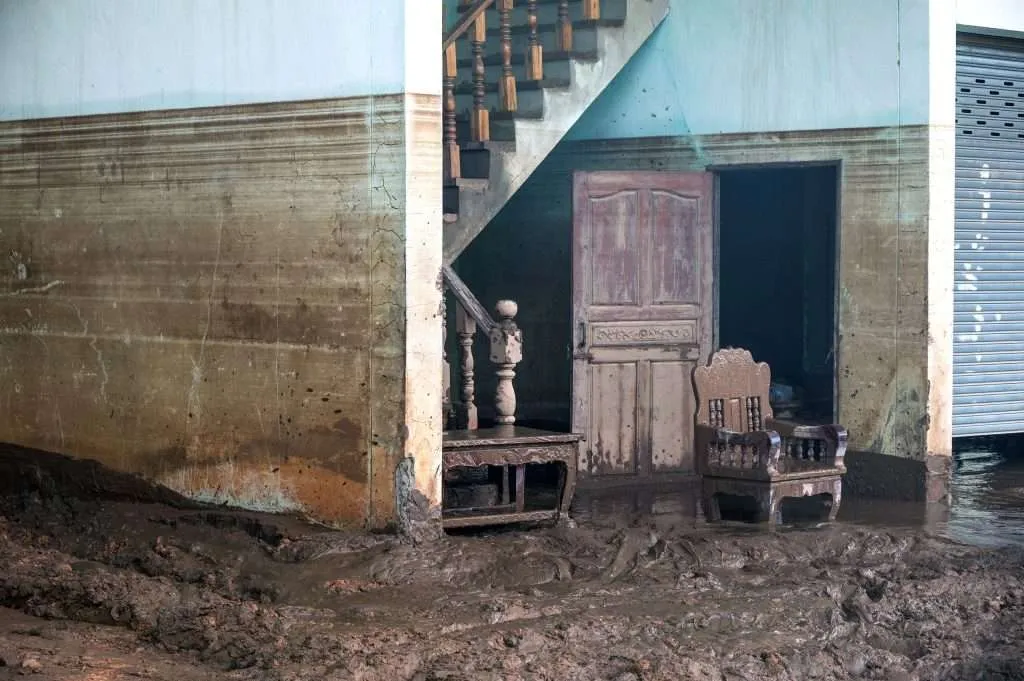
Flooding can leave your home unsafe, damaged and difficult to live in long after the water has gone. RSL Claims are independent flood damage insurance claim consultants helping homeowners assess the full extent of the damage, deal with insurers and negotiate fair flood damage insurance claim settlements.
Regulation
Experience
20+ years · Founded 2003
Response
24/7 support · On site within 24h
Full claim scope
Making sure your flood damage insurance reflects the true extent of the loss
The process
How we handle your flood damage insurance claim
From the moment you contact us, we manage the assessment, evidence gathering, insurer negotiations and repair process so you can focus on getting your home back to normal.
1
Inspecting the damage and reviewing your policy
We arrange a free consultation and inspect the flood damage as soon as possible. We review your policy wording, assess the source and spread of the flooding, and identify areas where hidden moisture or contamination may affect the claim.
2
Taking control of the claim process
Once appointed, we deal directly with your insurer and their loss adjuster. We help arrange emergency works, drying specialists, temporary accommodation and interim payments where appropriate.
3
Building evidence for the full claim
We prepare a detailed claim supported by photographs, damp readings, contractor schedules, drying records and repair costs to capture the full extent of the flood damage.
4
Challenging low or incomplete assessments
We negotiate with the insurer on your behalf and challenge attempts to limit drying, strip-out, reinstatement or settlement values where the evidence supports a wider claim.
5
Restoring the property and closing the claim
Our vetted contractors can carry out the agreed repairs, with your approval throughout. We continue managing the process until the works are complete and the claim is fully resolved.
Recently experienced flooding at home?
Speak to an independent flood damage insurance claim consultant before decisions are made on drying, strip-out or settlement. Free consultation, no obligation.
Recent settlements
+30–50% above insurer’s first offer
Range achieved across recent claim settlements. We treat each claim on its own merits – and never settle for the first number on the table.
Founder · Chartered Loss Adjuster
Talk to the founder
Flood claims are often under-settled because the real damage is hidden beneath the surface.
Moisture beneath floors, contamination and rushed drying can all affect the true cost of repairs. The earlier we get involved, the easier it is to evidence the full impact of the flooding and protect the value of the claim.
Rob Spence – Managing Director, Chartered Loss Adjuster.
Frequently asked questions
Common questions about flood damage insurance claims
What should I do immediately after flooding in my home?
Your safety comes first. Avoid entering areas where electrics may be affected and contact emergency services if needed. Take photographs of the damage where safe to do so and try not to dispose of damaged items before they have been recorded.
Does home insurance cover flood damage?
Many buildings and contents insurance policies include flood cover, but the extent of cover depends on the policy wording, excesses and the source of the flooding. We help review your policy and explain what should form part of the claim.
How long does a flood damage insurance claim take?
It depends on the severity of the flooding, drying times, contamination levels and the extent of repairs needed. Smaller claims may resolve within a few months, while major flood losses can take longer. Early involvement helps reduce delays.
Why is professional drying so important?
Floodwater can leave hidden moisture beneath floors, inside walls and within structural materials. If drying is incomplete, mould, damp and further damage can develop later. We help make sure proper moisture monitoring and drying records are used throughout the claim.
Can I claim for alternative accommodation?
If your home can’t be safely lived in during drying or repairs, your policy may cover the costs of temporary accommodation. We help present this clearly to the insurer and include reasonable costs within the claim.
What if my insurer says only part of the damage is covered?
Flood damage often spreads beyond the visibly affected areas. We carry out an independent assessment, gather supporting evidence and challenge decisions where the insurer’s position doesn’t reflect the true extent of the loss.
Can floodwater contamination affect the claim?
It can, as floodwater can contain sewage, chemicals, silt or bacteria depending on the source of the flooding. This can affect what needs cleaning, replacing or stripping out as part of the reinstatement works.
Do I need to use the insurer’s contractors?
No, you can usually choose your own contractors for repairs and reinstatement works. We help review the insurer’s proposed scope of works, challenge anything that appears incomplete and, where needed, arrange trusted contractors to restore your property.
Get in touch
Free, no-obligation consultation on your home insurance claim for flood damage
Tell us briefly what happened and we’ll come back to you as soon as possible. If we can help, our FCA-regulated loss assessor will tell you honestly. If we can’t, we’ll point you in the right direction. We cover the North West of England and North Wales – and travel further than 100 miles when a claim warrants it.
Water
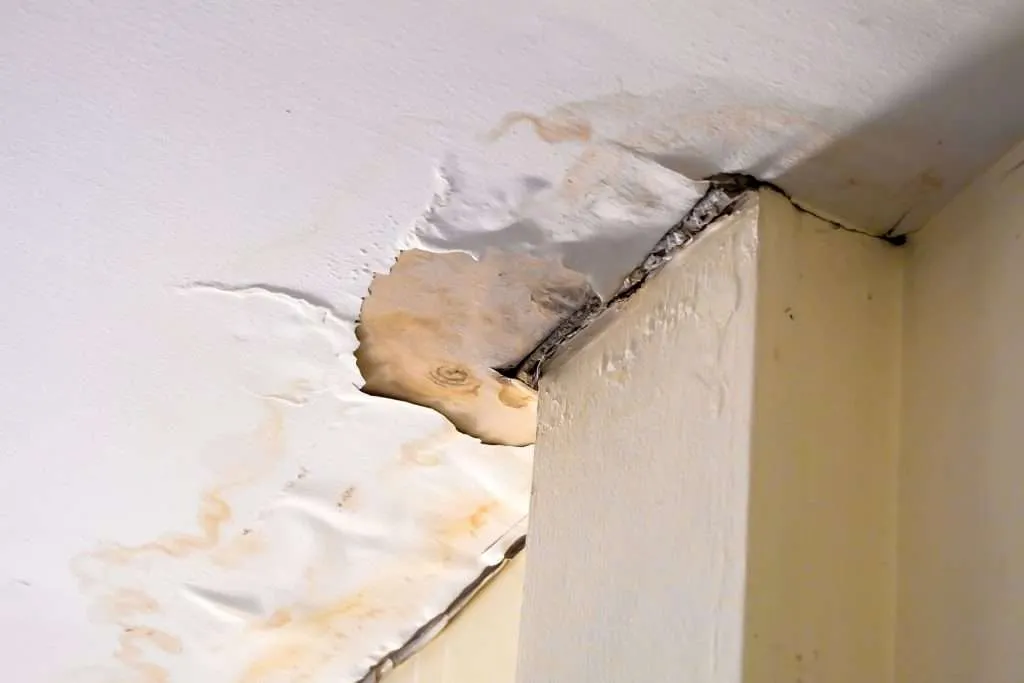
Burst pipes & water damage
We help identify the source of damage, coordinate drying and repairs and present the full claim to your insurer.
Storm
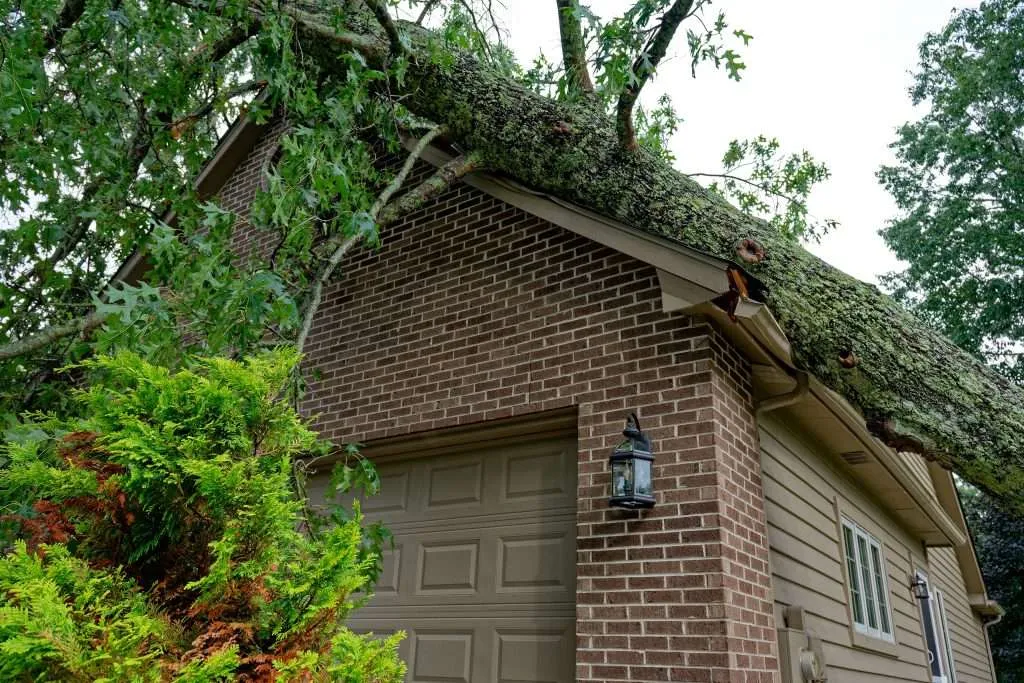
Storm damage
Roof damage, fallen trees and water ingress claims are professionally documented and negotiated.
Fire
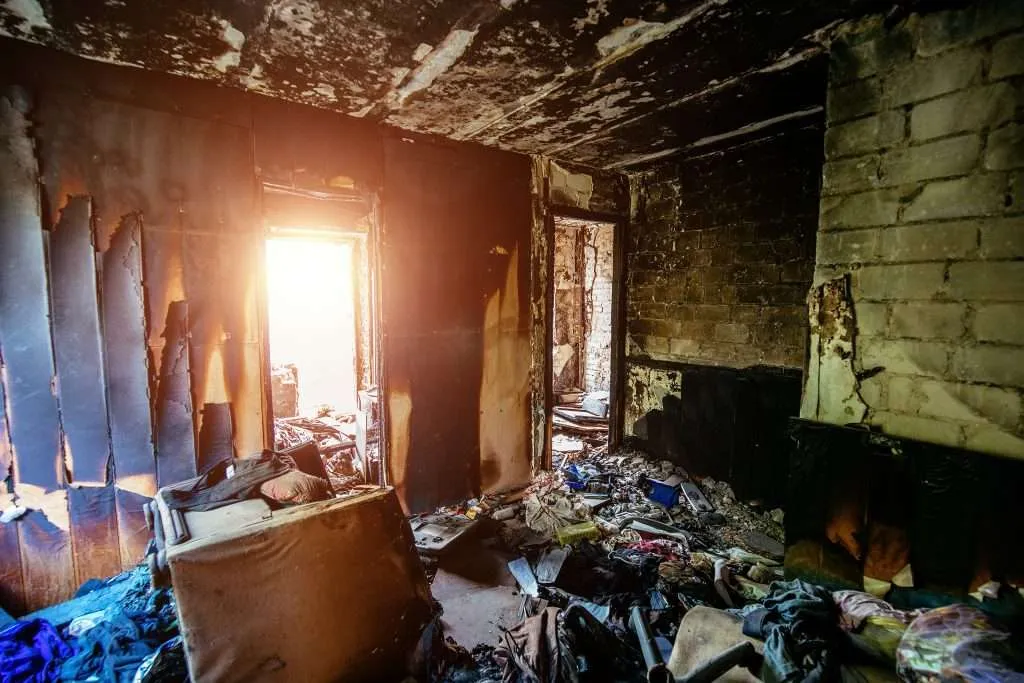
Fire damage
From kitchen fires to major property losses, we manage the assessment, repairs and negotiations on your behalf, working to help you receive a fair settlement.